

Sumio: Net Worth Tracker analysis by Appwee
I approached Sumio: Net Worth Tracker as a practical finance app rather than a complete banking replacement. Its purpose is to help me gather a picture of my net worth, investments, stocks, funds, and other assets in one place. That sounds simple, but it solves a real everyday problem: money is often scattered across a bank account, a retirement plan, a brokerage account, a savings goal, and physical assets that are easy to forget when I think about my overall financial position.
After using it, my impression is that Sumio is most useful when I treat it as a personal financial dashboard. It encourages a wider view than a normal banking app, which usually focuses on cash held with one institution. The experience is not aimed at people who want a sophisticated trading terminal or detailed tax software. Instead, I see it as a lightweight way to record what I own, follow changes over time, and make financial conversations with myself more concrete.
The app is free to install, with optional in-app purchases ranging from $2.99 to $29.99 per item. It is published by Fiduciary and has an Everyone content rating, so its basic audience is broad. Its average rating is 3.8 from around 78 ratings, with 10K+ installs, which suggests a modest but established user base rather than a huge mainstream finance platform. The current version is 1.9.18, and it supports Android 7.0 or later.
Getting from installation to a useful money picture
What I would prepare before opening it
For a first-time user, the best preparation is not a collection of passwords or a stack of financial documents. I would begin with a rough inventory of accounts and assets: everyday cash, savings, investments, funds, stocks, property, vehicles, or anything else I genuinely want included in my personal balance sheet. The goal is not perfect precision on the first screen. The goal is to create a sensible starting point that can be improved later.
This distinction matters because a net worth tracker is only as helpful as the information I choose to maintain. If I enter one investment account but forget a major savings account or debt, the resulting total may look reassuring while being misleading. I therefore recommend making a private checklist before setup. It takes little time and prevents the common mistake of confusing “the accounts I remembered today” with “my complete financial position.”
I also found it useful to decide what I want the app to answer. Am I trying to see whether my investments are growing? Do I want to compare assets with liabilities? Am I preparing for a monthly money review? Or do I simply want one place to record scattered holdings? A clear purpose makes the first setup less overwhelming and helps me avoid entering details that I will never maintain.
How I would handle the first setup
I would start with the most stable, easiest-to-identify items rather than trying to reconstruct every transaction. Cash accounts and clearly understood assets provide an immediate foundation. Once those are represented, I would add investment holdings and funds carefully, checking names and values as I go. This staged approach is better than rushing through a large list and later wondering which number belongs to which account.
Sumio’s value comes from aggregation at the personal level, so I would use consistent labels for similar items. For example, separating emergency savings from spending cash makes the overview more meaningful than placing everything under one vague category. Likewise, keeping long-term investments distinct from short-term holdings helps me understand not just how much I own, but what role each part plays.
One practical tip is to record the date or context of an unusual value in my own notes outside the app. If an asset is temporarily valued differently because of a sale, transfer, or market movement, I want to remember why the total changed. A tracker can show the number, but good financial review also depends on remembering the story behind that number.
The first successful action
For me, the first meaningful success would be seeing a complete-enough net worth figure that includes more than one type of asset. That moment is more useful than merely opening the dashboard. I would add a few core holdings, review the combined view, and ask whether it reflects my real financial life. If it does, Sumio has already done something valuable: it has turned disconnected figures into a single reference point.
I would then take a screenshot or write down the starting total privately, not because the number is final, but because a baseline makes future reviews worthwhile. Checking a tracker repeatedly without a starting reference can become a habit with little insight. Checking it at sensible intervals can show whether saving, investing, spending, or market changes are moving me in the direction I expect.
A second useful action is to correct an obvious imbalance immediately. Perhaps investments are included but savings are not, or a personal asset is listed while a liability has been overlooked. This is where the app becomes more than a calculator. It prompts me to challenge the assumptions behind my financial snapshot instead of accepting the first total as truth.
Where beginners may become confused
The phrase “net worth” can create confusion because it is not the same as available cash. A person may own investments or other assets and still have limited money for this week’s expenses. Sumio can help display the broader picture, but I would never use the net worth total as a spending limit. For day-to-day budgeting, a dedicated banking or budgeting tool may be more appropriate.
Investment values can also change for reasons unrelated to personal saving. A portfolio total may rise or fall because market prices move, not because I deposited or withdrew money. That means I should interpret changes alongside my own activity. If I want to understand performance precisely, I may still need the original brokerage or fund provider, where transaction history and investment-specific details are usually more comprehensive.
Another possible source of friction is the difference between manually maintained information and automatically synchronized information. I would not assume that every account updates itself simply because the app is designed to track several financial categories. Before relying on the dashboard, I would check how each figure is entered and how often I need to refresh it. A number that is two months old can still be useful as a reference, but it should not be mistaken for a live balance.
There is also a psychological trap: focusing too much on the headline total. A higher net worth is generally encouraging, but the composition matters. A large amount tied up in an illiquid asset is different from accessible savings. A portfolio concentrated in one area carries different risks from a spread of holdings. Sumio helps me gather the categories, but the judgment about liquidity, concentration, and risk remains mine.
How I would build a repeatable routine
Once the initial setup is complete, I would avoid opening the app randomly throughout the day. That can turn normal market movement into unnecessary anxiety. A scheduled review is more productive. During that review, I would update changed values, check whether every major account is still represented, and compare the overall direction with my personal goals.
A useful workflow is to review stable assets first, investments second, and unusual items last. Stable assets establish the foundation. Investments explain much of the movement. Unusual items, such as a recently sold possession or a temporary balance, deserve a final check because they can distort the overall picture. This order keeps the process focused and reduces the temptation to react emotionally to one changing figure.
I would also separate “maintenance” from “decision-making.” Updating a value is maintenance. Deciding to save more, reduce spending, change an investment, or delay a purchase is a separate decision that should not be made automatically from one dashboard view. The app is strongest when it gives me organized information; it should not replace careful consideration or professional advice for complex financial choices.
A realistic everyday example
Imagine I am preparing for a monthly money check-in. My spending account looks healthy, but I also have a savings balance, a small stock portfolio, and a fund held elsewhere. Looking only at my bank app would show part of the story. In Sumio, I can bring those pieces together and see whether my overall position has improved since the previous review.
If the total has increased, I can ask whether the change came from saving, investment movement, or an asset update. If it has decreased, I can distinguish a temporary market decline from a genuine reduction in savings. That distinction prevents a common overreaction: changing a long-term plan simply because one month’s total looks uncomfortable.
The same workflow can help before a major purchase. I would not ask only, “Can I pay for this?” I would also ask, “What will this do to my assets, cash buffer, and longer-term position?” A net worth view adds context that a simple account balance cannot provide. It does not make the decision for me, but it makes the trade-off harder to ignore.
Where it fits beside familiar alternatives
Compared with a standard banking app, Sumio offers a broader personal view because it is designed around net worth and multiple asset types rather than one institution’s accounts. That makes it attractive to someone whose finances are spread across providers. A banking app is usually better for immediate transactions, current cash availability, and payment activity.
Compared with a dedicated investment platform, Sumio is more general. It can help me place stocks, funds, and other assets into a wider personal context, but I would still turn to the investment platform for detailed orders, research, portfolio analytics, or account-specific records. The trade-off is breadth versus depth.
Compared with a traditional budgeting app, Sumio appears better suited to balance-sheet awareness than category-by-category spending control. If my main problem is overspending on food, subscriptions, or transport, a budgeting tool with transaction categorization may serve me better. If my main problem is not knowing what I own across different places, Sumio is the more relevant starting point.
Who should use it, and who should skip it
I would recommend Sumio to people with a few scattered assets who want a clearer personal overview without committing to a complex financial system. It can also suit beginners who are starting to invest and want to understand how investments fit into their wider finances. The simple concept makes it approachable, provided the user is willing to keep entries accurate.
I would be more cautious recommending it to someone who expects a fully automated, institution-connected financial command center. I would also point advanced investors toward a specialist portfolio tool if they need detailed performance calculations, trading functions, or deep tax reporting. Likewise, someone focused almost entirely on weekly spending may get more value from a budgeting-first app.
Users should also think about their tolerance for manual upkeep. A tracker is not a “set it and forget it” product if values or accounts need attention. The benefit comes from returning with a purpose and keeping the picture reasonably current. If I know I will abandon any app that requires occasional updates, I should choose a tool whose automation and workflow match that preference more closely.
Privacy-minded habits and financial discipline
Because this is a finance app, I would approach it with the same care I use for any tool that contains personal money information. I would avoid entering more detail than I need for the decision I am trying to make, and I would keep my device protected. I would also treat the displayed totals as personal planning information, not as something to share casually.
There is a useful discipline in keeping the app descriptive rather than emotional. I would not use it to chase market gains or to compare my finances with other people. Its best role is quieter: establish a baseline, maintain a coherent snapshot, and use that snapshot to make better questions possible.
My next step after the first review
After creating the first overview, I would choose one improvement rather than trying to optimize everything. That might mean adding a forgotten savings account, separating two asset categories, or setting a regular review reminder in my own calendar. Small corrections create a more trustworthy dashboard than a rushed attempt at total perfection.
I would also revisit whether the app is answering my original question. If I wanted net worth awareness, the combined view should make that easier. If I actually wanted detailed spending control or investment analysis, I would pair it with a more specialized service instead of expecting Sumio to cover every financial task.
Overall, I found Sumio: Net Worth Tracker most convincing as a simple organizing layer for personal finances. It is free to start, broad enough to include savings and investments together, and approachable for someone taking a first serious look at their financial position. Its limitations are equally important: the value depends on accurate upkeep, a net worth total is not a spending balance, and specialist tools remain better for detailed budgeting or investing.
My recommendation is to begin with a small, honest snapshot and judge the app by whether it helps you understand your money more clearly after that first review. If seeing your scattered assets together gives you a better basis for decisions, Sumio is worth trying. If you need live banking operations, advanced portfolio analysis, or strict expense tracking, I would choose a more focused alternative and use this kind of tracker only as a complementary overview.
Gallery
Sumio: Net Worth Tracker Pros and Cons
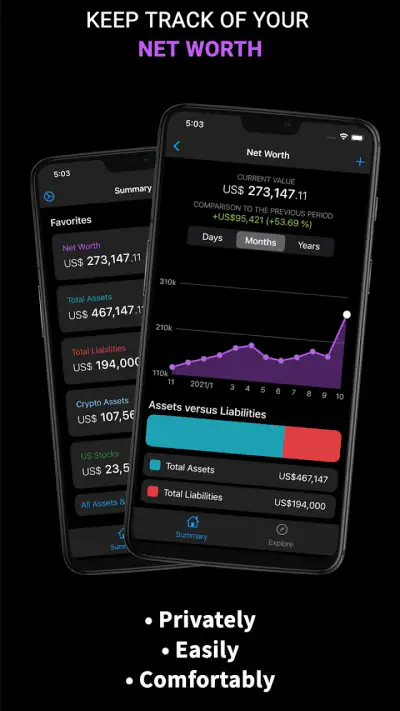
- Tracks assets
- debts
- and net worth in one organized dashboard.
- Supports multiple currencies for users managing international finances.
- Custom categories help tailor accounts and investments to your situation.
- Charts make changes in wealth easier to understand over time.
- Useful reminders can encourage regular financial updates.
- Manual data entry may become tedious without automatic account syncing.
- Some advanced features may require a paid subscription.
- Estimated property or asset values can quickly become outdated.
- Financial insights depend on keeping every account updated accurately.
- Privacy-conscious users may hesitate to store sensitive financial details.
Sumio: Net Worth Tracker Frequently Asked Questions
What is Sumio: Net Worth Tracker used for?
Sumio: Net Worth Tracker is a personal finance app designed to help you monitor your overall financial position in one place. You can record assets such as bank accounts, investments, property, and digital currencies, then subtract liabilities like loans or credit card balances. Its main purpose is to show how your net worth changes over time rather than simply tracking everyday spending.
How do I add my accounts and financial information to Sumio?
After installing Sumio, you can generally create your financial profile by adding assets and liabilities manually. Depending on the version, region, and available integrations, some users may also be able to connect supported financial accounts or services. Before entering sensitive information, check which connection methods are offered, what permissions are requested, and whether manual tracking is more suitable for your privacy preferences.
Is Sumio: Net Worth Tracker free to download and use?
Sumio can typically be downloaded without an upfront charge, but some features may require a premium subscription or in-app purchase. Advanced tools, additional tracking options, historical insights, or expanded customization may be restricted depending on the current plan. It is worth reviewing the pricing page and subscription terms in the App Store or Google Play before starting a trial.
Does Sumio automatically update net worth and investment values?
The level of automation depends on the accounts and services supported by your version of Sumio. Connected accounts may update balances automatically, while unsupported assets, property values, cash, collectibles, or private investments may need to be entered manually. Even when automatic updates are available, occasional checks are recommended because financial data can be delayed, incomplete, or affected by connection errors.
Is Sumio safe for storing personal financial information?
Sumio is intended for sensitive financial tracking, so users should review its privacy policy, security explanations, and requested permissions before adding real account information. Avoid sharing passwords or verification codes outside the app, enable device security such as a passcode or biometric lock, and keep the application updated. Remember that no online service can guarantee absolute protection from every security risk.














